Under Regulation (EU) 2025/40 (effective 12 August 2026), a company's PPWR obligations are determined by its economic operator role — not its commercial title — and one company can hold multiple roles across…
The EU’s Carbon Border Adjustment Mechanism (CBAM) is moving from reporting to payment, forcing importers to shift from emissions tracking to financial forecasting.
While sustainability is often viewed through an environmental lens, the three pillars of sustainability - environmental, social, and economic - offer a more holistic framework that reflects the full scope of its impact.
This article breaks down the current CBAM sector scope, providing a detailed guide on which goods are covered, how to identify if your imports are in scope, and what steps to take to ensure CBAM compliance.
EFRAG's November 2025 Amended ESRS package cuts mandatory datapoints by 61%, removes all voluntary datapoints and introduces a streamlined double materiality assessment, with fair presentation replacing prescriptive…
Under the EUDR, operators, any company first placing or exporting a regulated commodity on the EU market, must conduct full due diligence, submit a DDS before every shipment, and retain documentation for at least…
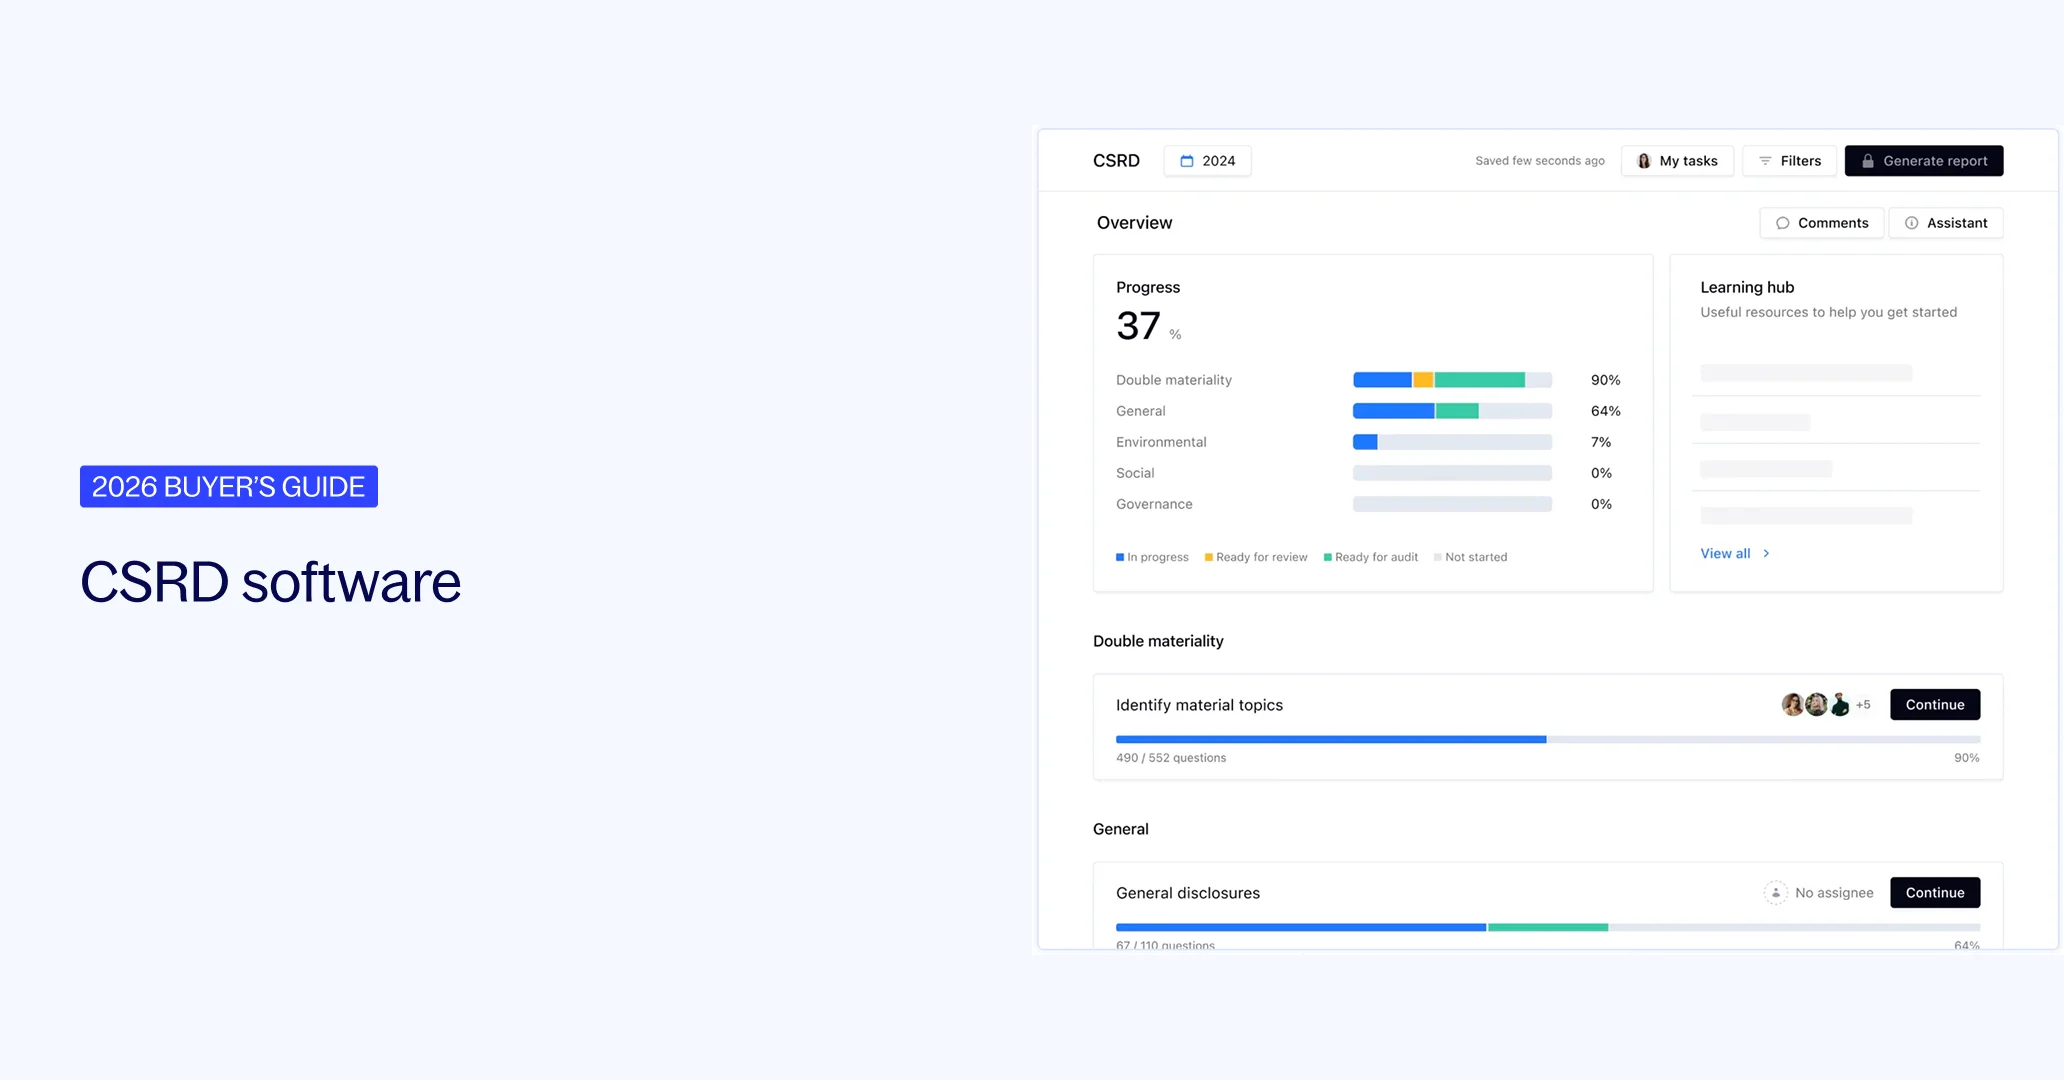
Following the December 2025 Omnibus I approval, CSRD now applies only to companies with more than 1,000 employees and net turnover exceeding €450 million, with first reporting from financial year 2027.
The PPWR (Regulation (EU) 2025/40) holds importers legally accountable under Article 18 for verifying supplier conformity assessments, collecting Declarations of Conformity (DoCs) per packaging type, and producing…
The PPWR (Regulation (EU) 2025/40) requires a manufacturer-issued Declaration of Conformity (DoC) for every packaging type placed on the EU market from 12 August 2026.
The Omnibus package reshapes CSRD in practice by narrowing mandatory scope, delaying Wave 2 reporting through the stop-the-clock measure, and setting the direction for simplified ESRS.
Following the December 2025 Omnibus changes, CSRD now applies only to companies with more than 1,000 employees and €450M+ turnover, with reporting starting in 2027 and simplified ESRS standards expected mid-2026.